

Thank you!


Your Loan Estimate will be sent to the email address you provided on the Soft Credit Check form. Please complete the Employment & Declarations portion of the application. It is important you DO NOT apply for or acquire new credit debt during the loan process. DTI increase might decrease your chances for approval as well as the potential negative impact to your credit FICO score.
The Loan Journey
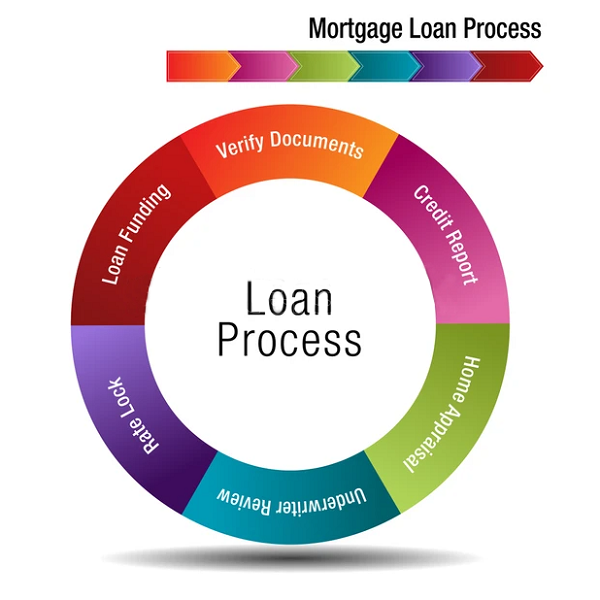
Before processing: The borrower submits an application with help from Mortgage Automated.
During processing: The file is built, checked, and verified for accuracy.
After processing: The file goes to underwriting for risk assessment and a decision.
Mortgage loan processing and underwriting turn times typically range from 2 to 5 business days for an initial review, while the entire mortgage process from application to closing takes 30 to 45 days on average for the standard mortgage industry. Specific turn times vary by loan type, lender volume, and file complexity. However, Mortgage Automated preferred lender has closed & funded many loans at the minimum of 13 days as allowed by compliance. This is only in regards to Owner Occupied properties and second home. Investment property turn times are dependent on the customer cooperation in providing necessary documents for credit approval and funding. There is not waiting period for Investment Properties, these loans can approve and fund in a few days!
Turn Times by Stage
Initial Underwriting Review: 2 to 3 business days for a lender to look at a newly submitted file.
Conditional Approval/Resubmission: 2 to 4 business days each time new documents or condition fixes are uploaded.
Appraisal and Title Work: 7 to 10 days to order, complete, and review property evaluations.
Closing Disclosure (CD) Period: 3 business days mandated by federal law before final signing.
Turn times are dependent on the customers cooperation in providing the necessary documents for credit approval. When the homeowner cooperates, the application can be submitted one week and funded the next week.
Common Factors Affecting Speed
Loan Program: Conventional and FHA loans often feature fast initial review turn times (2–3 days), whereas government-backed programs like USDA or specialized non-QM files can add extra days for secondary agency reviews.
Document Readiness: Quick responses to lender requests for asset or income verification prevent processing stalls.
Lender Workload: High market application volumes can stretch standard review windows significantly.
On a rare occasion, we need to request documents from the local county and this takes time. Appraisal turn times are less than one week and paid upfront. Title and escrow only take a few days to clear. The most common factor affecting speed is the customer unresponsiveness or failure to provide the adequate necessary document(s) for credit approval.